By Ammar Ashour
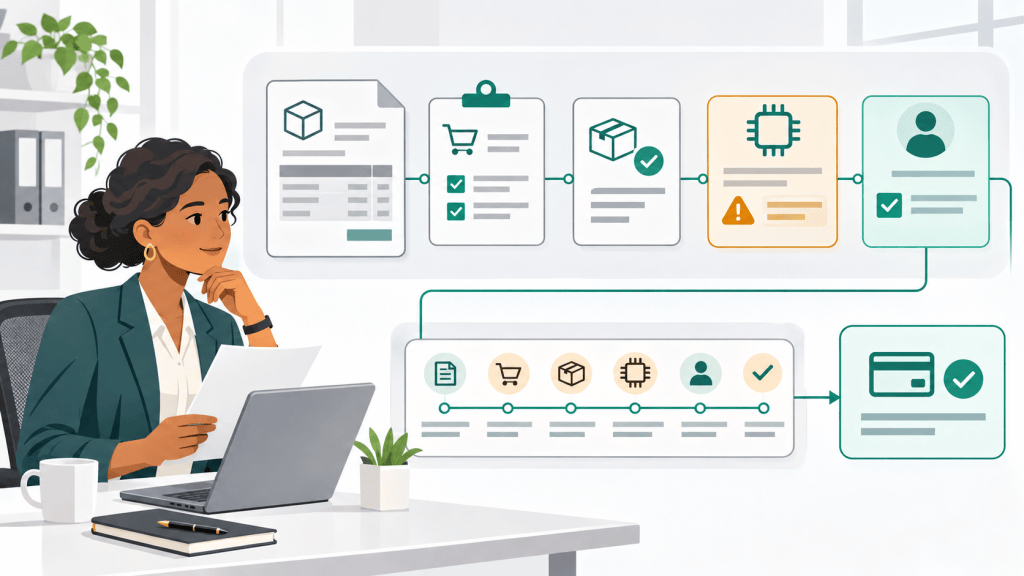
When AI helps review an invoice, the payment record should show more than the final “approved” status. A useful audit trail connects the original invoice, the business obligation, receipt of the goods or service, the AI flag or summary, the human review, the approval, the accounting-system history, and the final payment reference.
This guide offers a practical evidence-packet model for United States small-business accounting teams. It does not prescribe a legal retention period. The fictional example does not describe a client, supplier, or actual payment.
What should the payment trail explain?
A second reviewer should be able to answer seven questions without reconstructing the decision from scattered messages:
- What was requested? Identify the invoice, supplier, amount, currency, due date, and proposed payment destination.
- Why was it owed? Link the purchase order, contract, approved request, or another documented basis for the obligation.
- What was received? Keep the receiving record, service confirmation, milestone approval, or responsible owner’s confirmation.
- What did the AI review? Record the source references, checks performed, flag or extracted fields, timestamp, and known limitations.
- What did a person verify? Show the reviewer’s comparisons, missing evidence, corrections, and final classification.
- Who approved the payment? Identify the required approver and any exception owner.
- What happened in the system and at the bank? Connect the final accounting entry, change history, payment reference, and reconciliation result.
The NIST AI RMF Playbook suggests maintaining histories, audit logs, documented human oversight, overrides, exceptions, and accountable go or no-go decisions. In an invoice workflow, those ideas support a record that shows how the system assisted and how a person reached the final decision.
Build the packet in seven layers
1. Source invoice
Keep the original invoice in its received form when permitted by your process. Record the source channel, received date, supplier, invoice number, invoice date, amount, currency, due date, service period, and payment instructions. If the invoice was replaced or corrected, preserve the relationship between the versions.
2. Business obligation
Connect the invoice to the purchase order, contract, subscription, approved purchase request, or another documented authorization. The packet should show what was ordered, by whom, under which terms, and whether the invoice matches that obligation.
3. Receipt or performance evidence
Include the receiving record, delivery confirmation, service-period evidence, milestone approval, timesheet, or responsible owner’s confirmation, as appropriate. An invoice can be mathematically correct while the underlying goods or service remain unconfirmed.
4. Supplier and payment-destination verification
Record whether supplier identity and payment details matched the approved supplier record. If bank details changed, attach the separate verification record and the evidence of independent confirmation. The workflow in Supplier Bank Detail Changes: A Verification Workflow for Small Businesses provides a copyable model.
5. AI review record
Record the approved tool or workflow, the source records it examined, the checks it performed, the output or flag it produced, and the time of the review. Capture the specific reason for an alert—such as a duplicate invoice number, amount difference, missing purchase order, or changed destination—rather than storing only a score.
Do not duplicate sensitive information merely to document the AI step. Use authorized record references, masked values, or a controlled link when that preserves traceability with less exposure. Note any source the tool could not read and any field a person corrected.
6. Human review and approval
Identify the preparer, reviewer, approver, their decision times, the evidence reviewed, unresolved exceptions, and the reason for release, hold, correction, or rejection. If a person overrides the AI result, record what changed and why. An override is not automatically a problem; an unexplained override is difficult to evaluate later.
7. Final accounting and payment evidence
Connect the approved packet to the bill or expense record, journal or ledger reference when relevant, payment date, masked payment reference, and reconciliation status. Record any post-payment correction, returned payment, credit, or exception as a linked follow-up rather than overwriting the earlier decision.
See a complete fictional evidence packet
Fictional supplier Harbor Point Facilities sends invoice HPF-2284 for $3,840 for October maintenance services. An approved annual contract supports the monthly charge. The facilities manager confirms the October service period. The payment destination matches the existing supplier record.
An AI review compares the invoice with the contract, supplier record, and recent bills. It extracts the supplier, amount, service period, and invoice number, then flags a possible duplicate because the prior month’s invoice had the same amount. The reviewer confirms that the invoice numbers and service periods differ and classifies the alert as a valid recurring obligation. The required approver releases the bill, and the payment is later matched during reconciliation.
| Packet item | Fictional evidence | Why it matters |
|---|---|---|
| Invoice | HPF-2284, $3,840, October service period | Identifies the request and terms presented |
| Business basis | Approved annual maintenance contract | Shows why the charge may be owed |
| Performance evidence | Facilities manager confirms October service | Shows the service period was completed |
| Supplier record | Existing supplier and unchanged masked destination | Supports identity and payment-route comparison |
| AI review | Same-amount alert; source references and review time | Shows what the system compared and why it flagged |
| Human decision | Different invoice number and service period confirmed | Explains why the alert was cleared |
| Approval | Named approver, timestamp, and release decision | Shows authority for payment |
| System history | Bill entry and change history | Shows who created or changed the record |
| Payment and closeout | Masked payment reference and reconciliation status | Connects the decision to the final outcome |
This example does not prove that every recurring invoice is valid. It shows why the stored reason matters: a same-amount alert was cleared because distinct authorized service periods and invoice numbers were verified.
Use system logs without mistaking them for the whole record
Current Intuit guidance for the QuickBooks Online audit log says the log records sign-ins, settings changes, edits to records, and certain automated or third-party actions. It can show the date, user, and changes associated with a transaction. Intuit also explains that attachments can be added to bills, expenses, invoices, vendor credits, and other supported records.
Those features can support traceability, but the audit log does not by itself prove that the goods arrived, the service was completed, the supplier confirmed a bank change, or the approver examined the right evidence. Keep the business evidence and decision record connected to the system history.
Intuit currently states that QuickBooks Online audit-log events are available for two years. That is a product-availability detail—not a legal retention rule. Confirm the current product behavior and make sure your authorized recordkeeping process does not depend on a system view that may expire before your approved retention period ends.
Set retention from policy and requirements—not from this checklist
The correct retention period can depend on the record type, jurisdiction, tax requirements, contracts, disputes, insurance, and organizational policy. This article intentionally does not assign one universal number.
For U.S. federal tax recordkeeping, IRS Publication 583 explains that supporting documents such as invoices, paid bills, receipts, deposit slips, and canceled checks support entries in business books and tax returns. Use current professional advice and the organization’s approved retention schedule to decide how long each record must remain available.
Copy this payment evidence packet
| Field | What to record |
|---|---|
| Packet ID | Unique reference connecting every item below |
| Invoice source | Received channel, date, original file, supplier, invoice number, amount, currency, due date, and service period |
| Business obligation | Purchase order, contract, subscription, request, or other approval reference |
| Receipt or performance | Delivery, receiving, service, milestone, or owner confirmation |
| Supplier comparison | Supplier record matched, contact differences, and any verified change record |
| AI workflow | Approved tool or process, source references, checks performed, time, and limitations |
| AI result | Extracted fields, alert reason, differences, and confidence indicator if shown |
| Human review | Evidence compared, corrections, missing items, and classification |
| Override or exception | What changed from the AI result, why, and who authorized the exception |
| Approval | Approver, time, authority, and release or hold decision |
| Accounting record | Bill, expense, journal, or ledger reference and final coding |
| System history | Creation and change references, user or automated actor, and timestamps |
| Payment evidence | Payment date, masked reference, approved destination, and bank status |
| Reconciliation | Match date, reviewer, exception, or follow-up |
| Retention owner | Authorized location, access owner, applicable schedule, and disposition status |
Use stable references rather than copying the same sensitive document into several places. Restrict access to the people who need it, and test whether authorized reviewers can retrieve the packet without relying on a private inbox or one employee’s memory.
Test one packet from beginning to end
Select one fictional test payment—or one completed real payment under your approved review process—and ask a second reviewer to follow the packet from invoice to reconciliation. Record any missing link, inaccessible document, unexplained override, or unclear owner. Fix the record design before expanding the AI workflow.
For the earlier review stages, use Duplicate Invoice or Fraud? How to Review AI Payment Flags and the broader AI Invoice Fraud: 7 Checks Before Your Business Pays.
Sources checked November 3, 2026. General educational guidance for accounting workflow planning in the United States; not legal, tax, audit, cybersecurity, banking, or individualized financial advice. Cover image: AI-generated editorial illustration.

